Circular vs. Regenerative business models: Why you need both

In the quest for a more sustainable economy, two frameworks have risen to the top of the strategic agenda: the Circular Economy and Regenerative Business.

To the casual observer, they may seem like the same thing—both aim to move away from the traditional “take-make-waste” linear model. However, for the forward-thinking leader, the distinction between them is critical. One is a masterclass in resource efficiency, while the other is a blueprint for systemic health.

At Quest, we believe that understanding this nuance is the difference between a company that simply survives the transition and one that leads it.


Circular Economy: The logic of closing the loop

The Circular Economy is primarily a strategy for resource management. It is designed to decouple economic growth from the consumption of finite resources. The goal is to design out waste and keep materials in use at their highest value for as long as possible.

In a circular model, business success is defined by technical and biological loops. The core question of circularity is: “How can we keep this material in the system?”

  • Resource circulation: Using recycled content and ensuring products are 100% recyclable.
  • Product life extension: Moving from selling “things” to selling “services” (e.g., leasing models, repair, and refurbishment).
  • Efficiency: Minimizing the leakage of energy and materials out of the system.

Regenerative: The logic of healing the source

While circularity focuses on the flow of materials, regeneration focuses on the health of the source. You can have a circular model that is not regenerative. For example: a technical loop that uses massive amounts of non-renewable energy or relies on labor practices that don’t support human well-being.

Regeneration goes beyond the loop. It is a living-systems approach that asks: “How can our presence here make this ecosystem and this community healthier?” In a regenerative model, success is measured by Net Positive Impact:

  • Restoration: Does the business sequester more carbon than it emits?
  • Vitality: Does the sourcing of raw materials actively improve soil health and biodiversity?
  • Equity: Is the business revitalizing the local community and fostering resilience among its stakeholders?

How they differ

Instead of looking at these as the same goal, think of them as two different gears in the same machine. Here is how they compare across three critical business metrics:

  • The Primary Focus

Circular: Resource efficiency. It’s about the “Loop”— keeping materials in use and eliminating waste.
Regenerative: Systemic health. It’s about the “Source”—ensuring the ecosystems and communities that provide those materials are actually getting healthier.

  • The Definition of Success

Circular: Aiming for Zero. Zero waste, zero emissions, zero extraction of virgin materials.
Regenerative: Aiming for Net Positive. Increasing biodiversity, improving soil carbon levels, and building social equity.

  • The View of Nature

Circular: Nature is seen as a provider of biological nutrients that must be kept in a cycle.
Regenerative: Nature is seen as a living partner that requires active investment and restoration to remain resilient.

The Synergy: Circular by Design, Regenerative by Intent

The most impactful businesses today do not choose between these two; they integrate them. We call this being Circular by Design and Regenerative by Intent.

To visualize this, let’s look at a textile company:

  • A Circular approach ensures their polyester is recycled and recyclable, or that they have a “take-back” program where old clothes are turned into new fibers. It’s a closed-loop system that stops the flow to the landfill.
  • A Regenerative approach looks at the cotton fields. It ensures the cotton is grown using practices that capture carbon in the soil, restores local water tables, and pays farmers a living wage that revitalizes their village.

By combining the two, the company doesn’t just stop “taking”; it starts “giving back.” It closes the loop on waste while simultaneously “blooming” the environment it touches. As we move deeper into the era of CSRD (Corporate Sustainability Reporting Directive) and TNFD (Taskforce on Nature-related Financial Disclosures), the pressure on companies to show how they impact nature is intensifying.

Circularity is your tool for reducing your negative footprint. Regeneration is your tool for building a positive handprint.
Ready to take action?

At Quest, we help businesses navigate their circular and regenerative journeys by bridging the gap between ambitious goals and actionable design. Whether you are looking to close your material loops or restore the ecosystems your supply chain relies on, we provide the strategic blueprint for a nature-positive future.

TNFD: the next big thing in sustainability reporting. Here’s why.

You will have heard it here first. TNFD is about to become one of the most important acronyms in your sustainability strategy — and most businesses haven’t even googled it yet. That’s both a problem and an opportunity, depending on how quickly you move.

Let us explain.


From TCFD to TNFD

Cast your mind back to 2015. A voluntary framework lands quietly on the desks of sustainability teams everywhere. It’s called TCFD — the Task Force on Climate-related Financial Disclosures. Most businesses file it under “nice to know.” A handful of early movers take it seriously.

Fast forward a few years and TCFD is mandatory across the globe. The G7 commits to rolling it out across all member countries. It gets absorbed into the ISSB — the global standard-setter for sustainability reporting — and becomes the backbone of climate disclosure worldwide. What started as a voluntary task became, within a decade, one of the most consequential reporting obligations in corporate history.

Sound familiar? It should. Because TNFD is following the exact same script.

So what actually is TNFD?

TNFD stands for the Taskforce on Nature-related Financial Disclosures. Think of it as TCFD’s younger sibling built on the same logic, the same structure, and backed by the same institutional muscle. Where TCFD asked companies to disclose their climate risks, TNFD asks a bigger, messier and arguably more important question: what is your relationship with nature, and what happens to your business if that relationship breaks down?

Nature as in the water your factories use, the soil your raw materials grow in, the pollinators your agricultural suppliers depend on, and the stable climate that keeps your supply chain predictable. The things that don’t show up on a balance sheet; until they do, and by then it’s too late.

TNFD was launched in 2021 and at its core is the LEAP approach. A practical step-by-step guide for businesses to understand where they touch nature, what that means for their risk profile, and how to report on it credibly.

  • Locate: identify where your operations and supply chains physically interact with nature.
  • Evaluate: understand what your business takes from those ecosystems and what it gives back, mapping both your dependencies and your impacts.
  • Assess: define the risks and the opportunities
  • Prepare: turn those insights into a credible disclosure and, more importantly, an action plan that actually moves the needle.
Nature loss is accelerating, and businesses today are inadequately accounting for nature-related dependencies, impacts, risks and opportunities. Nature-risk is sitting in company cash flows and capital portfolios today. The costs of inaction are mounting quickly."
David Craig, Co-chair of TNFD

This is not a distant prospect

Here’s where it gets real. TNFD already has over 620 adopters across more than 50 countries, representing over $20 trillion in assets under management. More than 500 TNFD-aligned reports have already been published. The TNFD Forum — its broader community of engaged organisations — has over 1,800 members in 71 countries.

Those are not the numbers of a niche framework. Those are the numbers of something becoming a market standard. Even the EU’s CSRD now includes nature-related disclosure requirements aligned with TNFD. 

The machinery is in motion. The question is not if — it’s when.


Why acting now actually matters

Here’s the thing about TNFD that makes it harder than TCFD: nature risk is location-specific. Your climate footprint is the same whether your factory is in Belgium or Bangladesh. Your nature risk is not. It depends on which ecosystems you operate in, where your suppliers source from, what water sources your business draws on. That kind of granular, supply-chain-deep understanding takes time to build.

Right now, less than 1% of companies disclose their biodiversity impacts. That number is going to look very different in five years. The window to be an early mover and to actually benefit from it is open. But it won’t stay open forever.

Ready to take action?

At Quest, we help businesses turn TNFD from an acronym into an action plan. Whether you’re starting from scratch or building on existing sustainability work, we’ll help you understand your nature dependencies, identify your risks and opportunities, and build a strategy that holds up when the regulations arrive.

Ecosystem Services: Why they matter for business

Every business depends on nature. That’s not a statement of values: it’s an operational fact. Clean water, stable soils, pollination, flood regulation, climate moderation: these are services that ecosystems provide, and that the global economy relies on. The World Economic Forum estimates that more than half of global GDP (around $44 trillion) is moderately or highly dependent on ecosystem services. Most companies have no idea how exposed they are.

That’s starting to change. The Taskforce on Nature-related Financial Disclosures (TNFD) published its final recommendations in September 2023, and the first wave of voluntary disclosures is already underway. The EU’s Corporate Sustainability Reporting Directive (CSRD) requires large companies to report on biodiversity and ecosystem impacts from 2024 reporting periods onward. Supply chain due diligence frameworks are increasingly asking about nature dependencies. The ecosystem services question is moving from peripheral to central, faster than most organisations have prepared for.

What are Ecosystem Services?

Ecosystem services are the various benefits that humans derive from ecosystems. The interconnected living and non-living components of the natural environment offer benefits also offer key benefits and opportunities for organisations, but also pose severe risks. These services fall into four broad categories:

  • Provisioning services are direct outputs — fresh water, timber, fish, crops, fibre, genetic resources. Industries including food and beverage, pharmaceuticals, textiles and construction are directly exposed here.
  • Regulating services moderate natural processes — flood control, carbon sequestration, soil erosion prevention, water filtration, pollination, disease regulation. These underpin agricultural productivity, infrastructure integrity and operational continuity.
  • Cultural services include recreation, tourism and the social value people place on natural landscapes. Less tangible in balance sheet terms, but increasingly important for social licence and insurance valuation.
  • Supporting services are the foundational processes — nutrient cycling, soil formation, photosynthesis — without which none of the above function.

The gap between dependency and disclosure

Knowing that a business depends on ecosystem services is one thing. Being able to quantify, locate and disclose those dependencies is another. This is where most organisations currently sit: aware in principle, unprepared in practice.

The TNFD’s LEAP approach – Locate, Evaluate, Assess, Prepare – is designed to close that gap. It starts with geography: where are the interfaces between your operations and supply chain and natural ecosystems? That’s often where companies get stuck. Most environmental reporting to date has been global and aggregate. Ecosystem services are inherently local. A watershed risk in Karnataka is different from one in the Mekong Delta. A pollination dependency in Morocco does not translate to the same risk profile as one in Argentina.

Evaluating ecosystem conditions at those locations requires data that most companies don’t currently hold: biome integrity indices, species abundance data, habitat fragmentation metrics, water stress scores. Some of this is publicly available through platforms like the Global Biodiversity Information Facility (GBIF) or WWF’s Risk Filter — but interpreting it in a business context requires judgement and expertise that most sustainability teams have not yet built.

The hidden risks

Physical risks arise when ecosystem degradation directly affects operations or supply chains. Declining groundwater levels reduce agricultural productivity. Deforestation in source regions increases flooding and crop failure. Pollinator decline driven by pesticide use, land conversion and climate change threatens significant portions of global food production.

Transition risks arise from regulatory and market change. CSRD scope 3 requirements mean large EU-based companies must increasingly understand and disclose the nature impacts of their entire supply chain. Companies that cannot demonstrate ecosystem stewardship face the prospect of losing access to capital, markets or contracts.

Reputational risks are growing as biodiversity loss receives media and investor attention. The failure to disclose known nature-related risks or the appearance of greenwashing nature-positive claims carries increasing liability.

The opportunities that arise

Ecosystem services are not only a risk management issue, but also a source of competitive advantage for companies that move early. Businesses that invest in supplier ecosystem resilience through regenerative agriculture programmes, watershed restoration, or soil health initiatives for instance reduce their exposure to physical risk and build more stable supply chains.

Nature-positive product positioning is gaining traction with B2B procurement teams that face their own regulatory pressures. A manufacturer that can demonstrate low deforestation risk, verified pollinator-friendly sourcing, or measurable biodiversity net gain in its supply chain has a credible differentiator with large retail and financial clients.

Where to start?

A nature strategy that starts with tree planting has skipped the hard part. The hard part is understanding what your business actually depends on, where those dependencies are geographically located, and what condition those ecosystems are in.

A practical starting point for most organisations is a materiality screening: mapping your operations and key supply chains against priority locations using existing spatial data tools, identifying the top three to five ecosystem services that drive material business risk, and establishing a baseline condition assessment for those services. This requires structured methodology, decent data and the right tool to aggregate it, and the willingness to look at the answer honestly.

From that baseline, the strategic work begins: setting targets, identifying interventions, choosing disclosure frameworks, and building the internal capacity to sustain it. The companies doing this now will be significantly better positioned when disclosure requirements tighten and procurement due diligence becomes standard. The window to get ahead of this is narrowing.

Need help to get started? 

We can provide you with the right tool, methodology and approach to get TNFD-aligned and ready for what lies ahead!

Why Nature is material to every organization

Ask most companies outside agriculture, mining, or forestry whether nature is material to them, and the honest answer is usually “not really.” The evidence says otherwise. Nature dependence is distributed across the entire corporate value chain, not confined to sectors that obviously touch land and ecosystems, and it rarely shows up where people expect.

The scale is bigger than the obvious sectors suggest

The World Economic Forum estimated that roughly $44 trillion of economic value generation, over half of global GDP, is moderately or highly dependent on nature. Construction, agriculture, and food are the obvious exposed sectors, but four value chains alone, food, infrastructure, fashion, and energy, account for roughly 90% of humanity’s biodiversity impact, meaning most of that exposure sits inside supply chains companies rarely map for this purpose.

Research separating dependence from impact found that service-oriented sectors like retail, consumer goods, and technology hardware carry meaningful nature dependence too, just channelled through supply chains rather than direct operations. A company can score low on every conventional environmental metric and still carry real nature dependence, because dependence and impact aren’t the same axis. You can be exposed to a risk you’re not causing.

Water makes the point most plainly, because there’s no sector exemption from needing it. Data centres need it for cooling, EV production depends on water-intensive mining, and office buildings need it for basic sanitation, alongside the obvious cases of farming and manufacturing. Virtually every organisation is connected to the water crisis in some way, whether through direct consumption or through a supply chain that depends on it.

Why “we don’t touch nature directly” misses the point

This is what double materiality captures. TNFD and GRI frame nature exposure on two axes: financial materiality (whether ecosystem degradation threatens costs, supply, or asset values) and impact materiality (whether a company’s activities are degrading nature, whether or not that shows up on a balance sheet). The two often move together rather than cancelling out. Firms with greater nature dependence also tend to have a greater biodiversity footprint, a self-reinforcing cycle where operations depend on ecosystem services while degrading the same services they rely on.

Pharmaceuticals is a good example here. Globally, roughly half of all small-molecule drugs approved between 1981 and 2019 have been natural products, natural product derivatives, or close analogues. That’s a real, quantifiable dependency on biodiversity inside an industry nobody instinctively associates with nature risk.

The relationship also runs the other way productively. Wetlands regulate flood water, green infrastructure cuts urban heat, and mangroves and seagrass sequester carbon faster than terrestrial forests. Research into natural climate solutions found real mitigation potential specifically because those models included a biodiversity constraint, ruling out converting natural habitat or native grassland purely for carbon. Take biodiversity seriously as a constraint, and nature-based climate solutions don’t get weaker; they get better designed.

Finance makes this unavoidable

The clearest sign that nature materiality has moved beyond resource-intensive sectors is who’s reporting on it. Early TNFD reporters include AXA, GSK, Iberdrola, and UBS: an insurer, a pharma company, a utility, and a bank, none of them extractive industries. What they share is a loan book, underwriting portfolio, or investment portfolio that finances companies who do extract, so their exposure runs through what they fund rather than what they produce. 

Nature is everyone’s business: What this means in practice

Not every company needs the depth of assessment a mining company does, but “not material to us” should be a conclusion earned through an actual dependency and impact screen, not an assumption based on sector. Applying TNFD’s LEAP framework (locate, evaluate, assess, prepare) to a company’s actual supply chain and financing relationships, rather than just its own operations, is usually what surfaces exposure that a sector-based assumption misses entirely. This is no longer purely voluntary either: under the CSRD, in-scope companies must run a double materiality assessment covering ESRS E4 (biodiversity and ecosystems), meaning the screening question itself is becoming a compliance requirement rather than a purely voluntary exercise.

The Bottom Line

Nature dependence doesn’t respect the line between “obviously environmental” industries and everyone else. It runs through supply chains, financing relationships, and sourcing decisions. For most organisations, the honest starting position isn’t “this doesn’t apply to us.” It’s “we haven’t checked yet.”

Are you ready to take action for nature?

We can help you on your journey by engaging with your suppliers, setting your strategy, and defining your impacts and dependencies. 

Climate or Nature? Why the two have to be managed together

For most of the last two decades, climate and nature have run as parallel, separate conversations. Companies build a climate strategy around emissions and science-based targets, while biodiversity, land, and water get treated as a slower, secondary workstream. That separation was always somewhat artificial, and it’s becoming actively costly.

The science says they’re one system, not two

In December 2024, IPBES published its Nexus Assessment, the first comprehensive global assessment to examine biodiversity, climate, water, food, and health as one interacting system rather than five separate crises. Its central finding: these are interlinked crises that compound each other, and treating them separately tends to fix one while making another worse. They have been operating in isolation for too long.

Where treating them separately backfires, in both directions

The clearest failure mode is carbon-only land use. A single-species plantation grown purely to sequester carbon can look excellent on a carbon ledger while destroying the biodiversity the land previously supported, and large-scale bioenergy cropping carries the same risk at scale. The reverse is just as real: climate change is now itself one of the primary drivers of biodiversity decline, so a company running separate climate and nature strategies is managing two symptoms of the same pressure without connecting them.

The relationship also runs the other way productively. Wetlands regulate flood water, green infrastructure cuts urban heat, and mangroves and seagrass sequester carbon faster than terrestrial forests. Research into natural climate solutions found real mitigation potential specifically because those models included a biodiversity constraint, ruling out converting natural habitat or native grassland purely for carbon. Take biodiversity seriously as a constraint, and nature-based climate solutions don’t get weaker; they get better designed.

Why we frame it as nature first, climate within it?

At Quest, we treat nature as the overarching system and climate as one process operating inside it. Climate regulation is one ecosystem service among others, alongside water cycling, pollination, and soil formation. Carbon got a decade’s head start in corporate reporting because it was the easiest variable to measure, not because it was the most important one in the system. That’s a systems-thinking distinction: it means starting from the state of the underlying system and treating climate stability as one output of that system’s health. It’s the difference between managing a thermostat and understanding the building it’s attached to.

What running them together actually looks like

In practice, this is sequencing and shared infrastructure, not two parallel teams:

  • One materiality assessment, not two. The same supply chain and geography data that flags climate transition risk can flag nature dependency risk in the same pass.
  • Interventions get checked on both ledgers. A restoration or land-use project has to show a real biodiversity outcome, not just a carbon number, before it counts as a win.
  • Governance merges rather than duplicates. A climate governance committee and disclosure workflow built for TCFD can usually extend to cover TNFD, since it was designed to.

The Bottom Line

Climate and nature aren’t two different problems. They’re two lenses on the same system, and the biodiversity loss driving one is often the same biodiversity loss undermining the other. The science is about as settled as this gets, and the reporting frameworks are converging to make integration the default. Companies still running separate strategies aren’t being cautious. They’re working from an incomplete picture of their own risk.

Are you ready to take action for nature?

We can help you on your journey by engaging with your suppliers, setting your strategy, and defining your impacts and dependencies. 

Data traceability & availability: How to make it work for you

Every sustainability claim a company makes, whether it is about carbon, nature, or labor conditions, ultimately rests on the same foundation: can you actually trace where something came from, and do you have reliable data about it? For most companies, the honest answer is “only partially.” That gap between what a company claims to know and what it can actually verify is quietly becoming one of the biggest risks in corporate sustainability.

Why this is different to Data Quality

It’s tempting to file traceability under ordinary data hygiene, but isn’t, for a few reasons:

  • Most companies don’t own the data: The information you need — where a raw material was grown, which farm it came from, what conditions workers faced — sits with suppliers several tiers removed from you, who may have no obligation or incentive to share it.
  • The chain gets murkier with distance: Tier 1 suppliers are usually visible. Tier 2 and beyond — the actual farms, mines, and raw material processors — are where visibility collapses, and that’s often exactly where the highest-risk activity happens.
  • Verification is harder than collection: Getting a number from a supplier is one problem, but trusting that number is another. Data that hasn’t been validated can’t reliably support compliance claims or survive an audit.
  • It’s a market access issue: With the EU Deforestation Regulation in active enforcement and CSRD reporting obligations expanding, a broken traceability system can mean a shipment gets held at the border or an order doesn’t arrive on time.

Why it actually breaks down

1. Inconsistent data formats across suppliers: Duplicate lot numbers, mismatched supplier codes, and manual data entry errors mean that even when data exists, it doesn’t line up cleanly enough to trace a product end-to-end.

2. Field-level data capture gaps: Where data originates on the ground — a farm visit, a factory floor — matters enormously. Tools that require constant connectivity or aren’t available in local languages see far higher rates of skipped or incomplete data entry than offline-first, localized alternatives.

3. Partial adoption: A traceability system only works if every tier actually uses it. A platform that Tier 1 suppliers adopt but Tier 2 and 3 ignore just moves the blind spot one level down the chain.

4. No agreed metrics: Even when data is collected consistently, suppliers, regions, and industries often aren’t measuring the same thing the same way — different units, different definitions of a “batch” or “impact,” different baselines. Without a shared metric standard, data can be complete and still incomparable across the chain.

What can you do about it?

The good news: none of this requires solving every problem at once. A few concrete moves make the biggest difference. Design matters as much as technology: traceability tools live or die on adoption in the field, not in head office, and offline-first, mobile-first, multilingual data capture tools consistently outperform connectivity-dependent, single-language systems when it comes to how much data actually gets captured accurately at the source. Collection alone isn’t enough, either — confirming accuracy is where most programs fall short, so building in spot-checks, cross-referencing, or third-party verification for your highest-risk suppliers and commodities matters more than assuming self-reported data is reliable by default.

The remaining moves are about focus rather than more effort. Rather than building a system that flags everything, define a narrow set of exceptions that genuinely warrant follow-up. Finally, treat tier 2+ visibility as the actual goal — since tier 1 visibility is usually already reasonably solid, the real return on effort is pushing traceability one or two tiers further back, toward the raw material sources where risk (and the current data gap) is greatest.

The Bottom Line

Data traceability isn’t a problem you solve with one tool or one big platform rollout — it’s a problem you solve by being honest about where your visibility actually ends, and then systematically pushing that line further into your supply chain. The companies that treat this as core operational capability rather than a reporting afterthought are the ones who’ll be able to back up their claims when it matters.

Are you ready to make your supply chain more transparent?

We can help you on your journey by engaging with your suppliers.

The TNFD LEAP Approach in Practice

Understanding and communicating an organisation’s relationship with nature — its impacts and dependencies — is no longer optional. Doing so builds credibility with stakeholders and customers alike, while giving companies the foresight to anticipate environmental risks before they materialise. It also strengthens long-term resilience by embedding sustainability into strategic decision-making. And increasingly, it’s what investors and financial institutions expect: capital is flowing toward organisations that can demonstrate genuine environmental responsibility and alignment with global sustainability commitments.

The Taskforce on Nature-related Financial Disclosures published its final recommendations in September 2023. Since then, the question most organisations are sitting with isn’t whether to engage with TNFD — it’s how. The LEAP approach — Locate, Evaluate, Assess, Prepare — is the methodological backbone of TNFD. It sounds sequential and tidy. In practice, it’s messier, more iterative, and considerably more data-intensive than most organisations expect. Here’s what each phase actually requires.

Locate

The first phase asks you to identify where your business interfaces with nature, across direct operations and your supply chain. In practice, this is where most mid-sized manufacturers get stuck. TNFD defines four types of nature interface: direct land use, freshwater use, sea use, and climate. But the challenge isn’t the taxonomy. It’s geography. Ecosystem conditions vary enormously at a local level. A supplier in the Brazilian Cerrado sits in a very different risk context than a comparable supplier in central Europe. A manufacturing site drawing from a stressed watershed faces different exposure than one in a water-abundant region.

This typically means starting with your top-tier suppliers and your own production sites, then overlaying their locations against available biome and ecosystem data. Tools like IBAT (Integrated Biodiversity Assessment Tool), WWF’s Risk Filter, or ENCORE (Exploring Natural Capital Opportunities, Risks and Dependencies) can help screen priority locations. None of them replace site-level judgment, but they establish a credible starting point to map your highest-priority nature interface points, segmented by geography and ecosystem type.

Evaluate

Once you know where your interfaces are, you need to ask what your operations and supply chains depend on and what they affect. TNFD uses the ENCORE database to link sector activities to ecosystem service dependencies and impacts. Some typical dependencies include freshwater supply, climate regulation, soil formation (for raw material inputs), and pollination. Impacts typically include GHG emissions, water pollution, land use change, and species disturbance.

The honest reality for most organisations: you probably don’t have the data to do this rigorously across your full supply chain. TNFD acknowledges this. The approach doesn’t require perfection — it requires a credible assessment of what is material. Qualitative scoring based on sector and geography is legitimate at early stages, as long as data gaps are documented and disclosed. A useful shortcut: sector-level materiality assessments already exist for sectors and sub-sectors. TNFD’s sector-specific guidance — covering food and agriculture, chemicals, construction materials, and others — provides a starting framework that can be adapted without building from scratch.

Assess

The Assess phase is where the work becomes strategic. You’re converting what you know about dependencies and impacts into a risk and opportunity register, categorised by physical risks (ecosystem degradation affecting operations), transition risks (regulatory, policy, and market change), and systemic risks (tipping points that affect entire value chains).

Some of the highest-probability risks? Supply chain disruption from water scarcity or land degradation in key sourcing regions; procurement policy requirements from large retail or financial sector clients; and access to green finance contingent on nature-related disclosure. Opportunities are less often discussed but genuinely exist. Verified low deforestation risk, reduced water intensity, or biodiversity-positive sourcing practices have a credible differentiator in conversations where regulatory pressure is flowing upstream. This is especially relevant for those operating in regulated EU markets.

Prepare

The Prepare phase covers two things that organisations often conflate: disclosure and strategy. On disclosure: TNFD recommends 14 disclosures, structured around governance, strategy, risk management, and metrics and targets. For a first report, organisations should aim for qualitative coverage of all four areas, with quantitative metrics for the highest-priority locations or materials. The goal is a coherent narrative, not a comprehensive data table.

On strategy: disclosure is the output, not the point. The more important outcome is a set of decisions about where to invest in ecosystem stewardship, which suppliers require targeted engagement, and what targets to set that are measurable and time-bound. A note on targets: the Science Based Targets Network (SBTN) has published its first full corporate guidance for land, freshwater, and ocean. Aligning with SBTN standards — or at minimum with TNFD’s recommended metrics — gives targets credibility with investors and clients. Vague commitments like “improving our biodiversity footprint” are increasingly scrutinised. As always, think of KPIs and being SMART.

What a realistic first-year TNFD journey looks like

An organisation starting from scratch can complete a credible LEAP assessment in four to six months, with a dedicated internal resource and external support on data, stakeholder engagement, and methodology. The output typically includes: a nature-related risk and opportunity register; a priority location map; a disclosure narrative aligned with TNFD recommendations; and a hands-on roadmap for taking action.

That’s not a complete picture. TNFD itself frames disclosure as a multi-year learning process. What matters in year one is that the methodology is sound, the gaps are acknowledged, and the direction of travel is clear. The organisations that will struggle are those waiting for certainty before starting. The data won’t be perfect in year one. That’s expected, and disclosed. The window to get ahead of this — before it becomes a procurement or access-to-capital issue — is narrowing.

Are you ready to take action for nature?

We can offer you the right tool, methodology and approach to ensure your nature strategy goes under way. Contact us to find out more!

CSRD Biodiversity Reporting: What ESRS E4 requires

Most companies preparing for CSRD have spent the bulk of their effort on climate. ESRS E4, the standard covering biodiversity and ecosystems, is proving harder to meet in practice, and the standard where implementation gaps are widest.

ESRS E4 applies to companies that identify material biodiversity impacts, risks or opportunities through their double materiality assessment. The bar for ruling out materiality is higher than most companies assume. For any business with significant land use, freshwater use, or agricultural or chemical inputs in its value chain, a low-materiality conclusion is difficult to justify. And honestly, every business has an impact or dependency on nature.

What does ESRS 4 actually require?

For companies where biodiversity is material, the standard requires disclosure across four areas:

  • Policies and commitments. Describe any policies managing biodiversity impacts, and whether the company has commitments on no net loss, biodiversity net gain, or nature-positive goals.
  • Targets. Measurable, time-bound targets that reference specific ecosystems or locations where relevant. Generic commitments to “protect biodiversity” without defined scope won’t meet the standard.
  • Actions and resources. What the company is doing, including Biodiversity and Ecosystem Action Plans, what resources are allocated, and whether actions are on track.
  • Metrics. This is where E4 becomes demanding. Required disclosures include: Area of sites in or adjacent to biodiversity-sensitive areas, area under conservation or restoration management, changes in ecosystem extent and condition, and pressures on biodiversity: land use, water use, pollution, invasive species, climate

Most companies have not historically collected data at this level of granularity. Land use change at site or supplier level, water consumption disaggregated by watershed, chemical inputs and biodiversity effects: these are not standard outputs from existing reporting systems.

Where the gaps are showing up

The double materiality assessment. Many companies are scoring biodiversity at a high level of abstraction, using sector averages rather than site-specific analysis. The result is a materiality conclusion that may not survive scrutiny as auditors become more familiar with the standard.

Location-specificity. Unlike carbon, biodiversity impacts are inherently local. A site adjacent to a protected wetland carries different exposure than an identical facility in an industrial zone. ESRS E4 expects that distinction to be reflected in disclosures, which means companies need actual spatial data on where they operate and what ecosystems they sit alongside.

Targets. Many companies are declaring alignment with the Kunming-Montreal Global Biodiversity Framework’s 30×30 target without translating that into company-level commitments that are measurable and time-bound. The gap between aspirational alignment and reportable target-setting is significant.


A note on Omnibus

The EU Sustainability Omnibus proposals narrowed the scope of mandatory CSRD reporting. But companies that remain in scope face substantially the same substantive requirements under E4, and companies responding to supply chain pressure from in-scope businesses will encounter the same questions regardless.

Where to start?

Begin with the double materiality assessment and take it seriously. From there: map material locations using spatial data, identify key ecosystem dependencies and impacts per site or supplier tier, set specific targets against that baseline, and assess what metrics you can realistically collect now.

CSRD biodiversity reporting can’t be handled by extending an emissions reporting process. It requires different data, different methodologies, and different conversations inside the business. The companies that understand that now will be in better shape when the first assurance review arrives.

Need help to get started? 

We can provide you with the right tool, methodology and approach to get CSRd-aligned and ready for what lies ahead!

The Nature Blind Spot: Why measuring supply chain impact is hard

Most companies have gotten reasonably comfortable talking about carbon. Scope 1, 2, and even Scope 3 emissions have standardized methodologies, familiar units (tCO2e), and a decade of tooling built around them. Nature is a different beast entirely — and it’s quickly becoming the next frontier companies can’t avoid.

The core challenge is this: carbon is a single, fungible metric. A ton of CO2 emitted in Brazil has the same climate effect as a ton emitted in Germany. Nature doesn’t work that way. A liter of water withdrawn in a water-stressed basin in Kenya is not equivalent to a liter withdrawn in a rain-soaked region of Scotland. Biodiversity loss, deforestation, soil degradation, and water stress are all local, contextual, and multidimensional — which is exactly what makes them so hard to measure at scale, especially across a sprawling, multi-tier supply chain you don’t fully see into.

Why is this so urgent now?

Most companies’ direct footprint is the easy part to measure — you own the buildings, meter the electricity, and count the trucks. The supply chain is where nature impact actually concentrates, and where visibility drops off a cliff. No single supplier’s nature risk looks large enough to matter on its own. The real exposure comes from how those risks aggregate across the whole portfolio of sourcing relationships — which is much harder to see and much easier to underestimate.

In addition, these are the current trends that are pushing companies to take it seriously:

  • Regulation is catching up: The EU Deforestation Regulation (EUDR), the Corporate Sustainability Reporting Directive (CSRD), and emerging rules under CSDDD all require companies to understand and disclose nature-related impacts across their value chains — not just their own operations.
  • Voluntary frameworks are maturing fast: The Taskforce on Nature-related Financial Disclosures (TNFD) now has hundreds of companies aligning with its recommendations, and the ISSB is working toward its own nature-related disclosure standards. The Science Based Targets Network (SBTN) has published methodology for companies to set actual science-based targets for nature, not just carbon.
  • The data gap is real and well-documented: Early CSRD reporting cycles have shown that a large share of companies still lack adequate systems for measuring biodiversity impact, which creates both audit risk and reputational risk.
  • Investors and customers are asking: Nature risk is increasingly framed not as a compliance checkbox but as a genuine business resilience issue — droughts, pollinator collapse, and ecosystem degradation are supply disruption risks in their own right.

A practical way to start: You don’t need ‘perfect’ data

The most common reason companies stall is thinking they need complete, granular data before they can act. In practice, the opposite approach works better — start broad, prioritize, then get progressively more precise where it matters.

Screen your materiality first

Use available tools to identify where your supply chain intersects with nature-sensitive geographies or high-impact commodities, before trying to measure precise impact everywhere. Tools like ENCORE, the WWF Risk Filter Suite, WRI Aqueduct (for water), and Global Forest Watch (for deforestation) are widely used precisely because they let you screen at low cost before investing in detailed assessment.

Focus on high-impact commodities

Certain commodities — soy, palm oil, beef, cocoa, cotton — are disproportionately linked to deforestation, water stress, or land degradation. Concentrating early measurement effort here, rather than spreading thin across every input, tends to surface the most material risks fastest and gives you a natural entry point for supplier engagement or certified sourcing.

Follow a structured assessment approach

SBTN’s methodology is a useful backbone even if you’re not yet setting formal science-based targets: assess your footprint and dependencies (across land, freshwater, oceans, and biodiversity), prioritize locations based on ecological and business significance, then set targets and act. TNFD’s LEAP approach (Locate, Evaluate, Assess, Prepare) offers a similar structured entry point specifically for nature-related risk and disclosure.

The Bottom Line

Measuring nature impact in the supply chain is genuinely harder than measuring carbon: it’s local rather than global, multidimensional rather than singular, and concentrated in parts of the value chain companies often can’t see clearly. But “hard to measure perfectly” isn’t the same as “can’t be measured usefully.” Starting with materiality screening, focusing on high-impact commodities, and using a structured assessment framework gets a company from zero visibility to genuinely useful insight — well before every metric is standardized and every regulation is finalized.

The companies treating this as strategic groundwork now, rather than a future compliance problem, are the ones who’ll have real answers when stakeholders start asking harder questions.

Are you ready to take action for nature?

We can help you on your journey by engaging with your suppliers and guiding you on your nature strategy

The hidden risks lurking in your supply chain

Sustainability has finally entered the boardroom. But many companies still overlook one of their biggest blind spots: the hidden environmental and social risks buried deep within their supply chains.

It’s no longer enough to track carbon emissions at headquarters or publish a glossy sustainability report. Real impact and real risk lives further upstream: in farms, factories, forests, and freight. And unless those risks are understood and addressed, companies leave themselves vulnerable to disruption, liability, and reputational damage.

Let’s break down the most common and overlooked supply chain risks that are costing businesses more than they think.

Deforestation and Land Use Changes

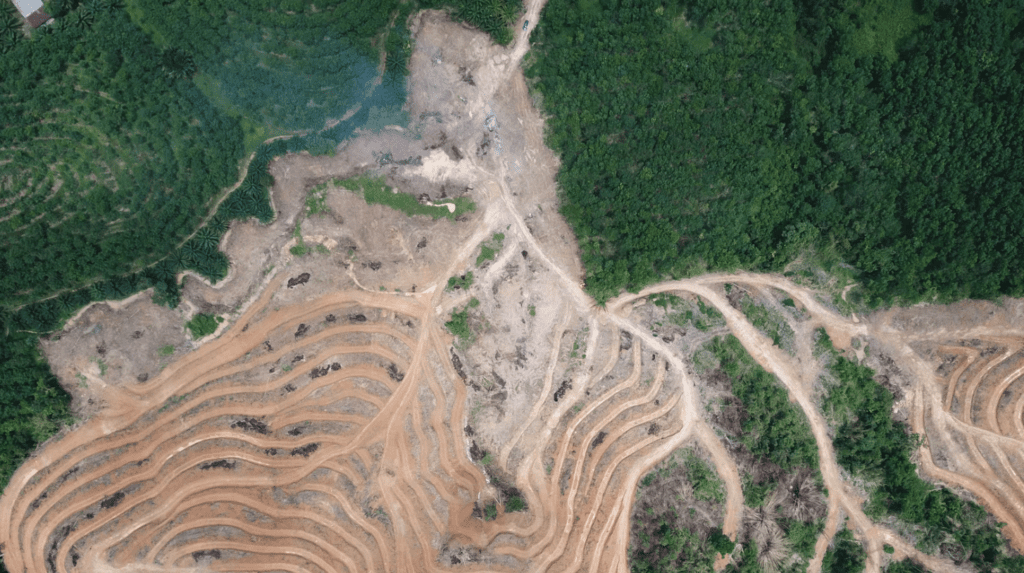
Your raw materials might be driving nature loss without you knowing it. Products like palm oil, soy, leather, cotton, and rubber are closely tied to deforestation, biodiversity decline, and land rights violations. Even if you don’t source directly from high-risk regions, indirect suppliers often do. Without traceability and no-deforestation commitments, brands risk contributing to ecosystem collapse and breaching emerging EU laws like the Deforestation Regulation (EUDR).

Labor Exploitation and Poor Working Conditions

Without people, you don’t have a product nor a service. And the truth is that still today, supply chains are more often than not built on hidden human costs. Wages below living standards, excessive working hours, unsafe environments, and even child or forced labor are still widespread in many sectors. With mandatory human rights due diligence legislation rolling out across the EU, these risks are now legal liabilities, not just ethical issues.

Water Scarcity and Pollution

We are running out water and the stats are alarming. Water is a key input in agriculture, textiles, and manufacturing but most companies don’t measure their water footprint beyond direct operations. In reality, their biggest water risks lie upstream. Suppliers in water-stressed regions may be competing with local communities for access or discharging untreated wastewater into ecosystems. These risks can trigger worker revolts, reputational damage, operational halts, or NGO-led campaigns.

Climate Vulnerability and Disruption

Climate risks in supply chains are not just about carbon. Floods, droughts, wildfires, and heatwaves are already disrupting harvests, logistics, and energy supplies, especially in vulnerable regions. Companies that fail to model these risks or build diversified, climate-resilient sourcing strategies may face shortages, price spikes, or product recalls.

What can be done?

Most businesses only track Tier 1 suppliers. But the real issues such as deforestation, forced labor, or biodiversity loss usually lie in Tiers 2, 3, and beyond. Without full value chain visibility, companies can’t act on risks or validate claims. And with growing investor pressure for Scope 3 disclosures, this opacity is a ticking time bomb.

Most supply chains are complex, global, and fast-moving. But that doesn’t mean they’re unmanageable. Supply chain due diligence is an increasingly important factor in a changing world (and we can help you managing it!). You can start by:

  • Mapping your upstream and downstream risks
  • Engaging suppliers to collect better data
  • Embedding ESG performance into procurement decisions
  • Setting credible targets for forests, water, human rights, and climate
  • Aligning with frameworks like TNFD

Are you ready to take action within your supply chains?

We can help you on your journey!